- ₹750-crore fresh issue and ₹342-crore OFS; price band fixed at ₹32–34
- IPO opens September 24 and closes September 28; listing proposed for October 1
- ₹325 crore earmarked for lending operations; ₹250 crore to strengthen NBFC subsidiary
- CFO Saurav Goyal cites AI-driven loan assessment amid DLG-related credit-risk questions
- FY26 revenue at ₹3,351 crore; reported net profit ₹242 crore
- Loan disbursals rise 31% to ₹23,099 crore; AUM reaches ₹22,520 crore
R MANICKAVASAGAM
AHMEDABAD, SEPT 23
Can artificial intelligence turn credit-risk assessment into a scalable growth engine for digital lending? That question took centre stage as Moneyview Ltd unveiled its ₹1,092-crore initial public offering (IPO), with the fintech company highlighting its technology-led lending model and addressing concerns surrounding Default Loss Guarantee (DLG) arrangements.
Moneyview’s IPO opens on September 24, with the price band fixed at ₹32–34 per equity share. The issue closes on September 28, while listing on the BSE and NSE is proposed for October 1.
The offering comprises a fresh issue worth ₹750 crore and an Offer for Sale (OFS) of 10.05 crore equity shares, valued at approximately ₹342 crore at the upper end of the price band. The total issue size is ₹1,092 crore.
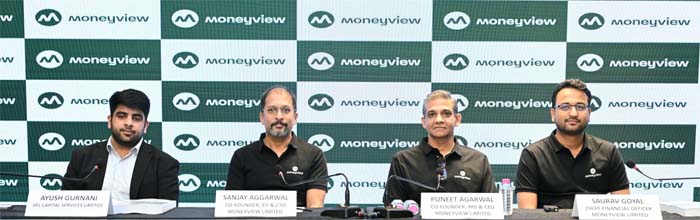
The company’s management, including CEO Puneet Agarwal, Executive Director and CTO Sanjay Aggarwal and CFO Saurav Goyal, outlined its business outlook at a media meet in Ahmedabad.
DLG: Growth accelerator or hidden credit risk?
With a substantial portion of the fresh proceeds earmarked for lending operations, the role of DLG emerged as a key investor concern.
Asked about the maximum financial exposure Moneyview could face if credit losses rose sharply, and the safeguards protecting the company, CFO Saurav Goyal said DLG provides lenders with a layer of protection against defaults.
He referred to the RBI’s 5% cap on DLG coverage under eligible arrangements and said Moneyview was using artificial intelligence to analyse the relevant risk factors before granting loans, with the objective of avoiding defaults.
The response places AI-led credit assessment at the heart of Moneyview’s risk-management narrative. However, the actual financial exposure under its DLG arrangements, the stress-testing framework and the extent of potential payouts remain important considerations for investors.
₹750 crore fresh capital to support lending
Of the ₹750 crore fresh issue proceeds, ₹325 crore is earmarked for supporting lending operations, including deployment under DLG arrangements, while ₹250 crore will be used to augment the capital base of its non-banking financial company (NBFC) subsidiary. The balance is intended for general corporate purposes.
The company has also described its broader capital deployment strategy as supporting lending growth, new products, technology, AI and IT infrastructure.
The IPO includes an OFS by existing shareholders, including promoters Puneet Agarwal and Sanjay Aggarwal, along with institutional investors. The OFS proceeds will go to the selling shareholders rather than the company.
Profitability meets rapid lending growth
Moneyview reported revenue of ₹3,351 crore and profit after tax (PAT) of ₹242 crore in FY26. In the first quarter of FY27, revenue stood at ₹1,065 crore and PAT at ₹174 crore.
“We are a profit-making company. We have shown a very strong consistent trajectory of profit growth with about ₹400 crore of profit after taxes before exceptional items in FY26,” Agarwal said.
Agarwal said the company’s profit trajectory and cash generation had influenced discussions with its board on the amount of fresh capital required to sustain its growth plans.
Disbursals surge; technology drives underwriting
Moneyview’s loan disbursals increased 31% to ₹23,099 crore in FY26. First-quarter FY27 disbursals rose 40% year-on-year to ₹7,152 crore.
Assets under management (AUM) stood at ₹22,520 crore as of June 30, 2026. The company serves approximately six million borrowers and has more than 140 million registered users, with around 80% of customers coming from Tier 2 and Tier 3 cities.
Its capital-light model relies substantially on lending partners, with approximately 75% of its loan book funded through Loan Service Provider arrangements.
The company processes around two lakh loan applications daily and uses more than one lakh data variables per borrower in its underwriting process, with minimal human intervention.
Digital lending beyond personal loans
Founded in 2014 by IIT Delhi graduates Puneet Agarwal and Sanjay Aggarwal, Moneyview launched its flagship digital personal loan business in 2017.
It has since expanded into earned wage access, home loans, loans against property, digital gold and UPI transactions. Its platform offers financial products across borrowing, transactions, investments and protection.
With its IPO proceeds intended to support lending expansion and technology investments, Moneyview is seeking to scale its digital-first model. For investors, the key considerations include sustaining profitability, maintaining credit quality and demonstrating that AI-led underwriting and DLG safeguards can manage risks as disbursals expand.
Bids can be made for a minimum lot of 441 equity shares and in multiples of 441 shares thereafter. The anchor investor bidding date is September 23.
Axis Capital, BofA Securities India, IIFL Capital Services and Kotak Mahindra Capital Company are the book-running lead managers to the issue.


