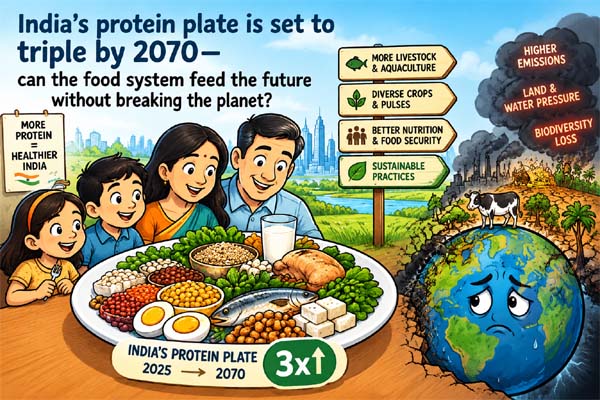
- ARE-FICCI study projects per-capita protein consumption to rise from 9.5 kg in 2025 to 30 kg by 2070
- Business-as-usual pathway could push annual protein-related emissions to 1.92 GtCO₂e
- Cumulative excess emissions could cross 44 GtCO₂e—nearly eight times the climate-safe annual threshold by 2070
- Pulses emerge as a major domestic opportunity, with consumption projected to rise to 9.3 million tonnes
- Integrated transition could bring annual emissions close to 0.30 GtCO₂e while opening new avenues for farmers, industry and investors
NE FOOD & HEALTH BUREAU
NEW DELHI, SEPT 16
What if India’s growing appetite for protein becomes one of the defining tests of its food security, farming economy and climate ambitions? A new study by Asia Research & Engagement (ARE) and the Federation of Indian Chambers of Commerce and Industry (FICCI) puts a striking number behind that question: India’s annual average per-capita protein consumption could more than triple—from 9.5 kg in 2025 to 30 kg by 2070.
The report, Charting India’s Protein Transition, warns that how India meets this additional demand could have consequences far beyond the dinner table. Under a business-as-usual pathway, annual protein-related emissions could reach 1.92 gigatonnes of CO₂ equivalent (GtCO₂e) by 2070, compared with an estimated climate-safe threshold of 0.25 GtCO₂e.
More dramatically, the modelling estimates that cumulative excess emissions could exceed 44 GtCO₂e by 2070.
The study therefore poses a larger question: Can India simultaneously deliver more protein, protect farmer livelihoods, build domestic food-processing capacity and keep the environmental cost of that transition within sustainable limits?
The protein transition is also a climate transition
The report arrives as India’s influence on global food demand continues to grow. India and Southeast Asia are projected to account for 31% of global agricultural and fisheries consumption by 2033, according to the OECD-FAO Agricultural Outlook 2024-2033.
The report’s modelling suggests that simply improving production efficiency will not be enough.
Measures covering methane emissions, feed, manure management, deforestation, energy use and food loss and waste could bring annual protein-related emissions down to 0.73 GtCO₂e by 2070.
But that would still be nearly three times the climate-safe threshold.
Greater diversification of protein sources could reduce the figure further to 0.50 GtCO₂e, while an integrated pathway combining production improvements and diversification could bring projected annual emissions to approximately 0.30 GtCO₂e.
The difference between these pathways is the heart of the study: the composition and structure of India’s future protein system may matter almost as much as how efficiently that system produces food.
Pulses: India’s traditional protein could become tomorrow’s opportunity
One of the report’s most significant findings concerns a food India already knows well—pulses.
Pulse-derived protein consumption is projected to rise from 3.5 million tonnes in 2025 to 9.3 million tonnes by 2070, making pulses the country’s second-largest protein category after dairy.
That projected expansion could create opportunities across the agricultural value chain—from farmers and processors to food companies and investors.
The report also highlights a striking domestic manufacturing gap: India currently imports almost 90% of its processed plant-protein isolates.
That dependence, the study suggests, could simultaneously represent a vulnerability and an opportunity to develop domestic processing, value addition and higher-value plant-protein manufacturing.
For Indian agriculture, the protein transition could therefore become more than a question of consumption—it could become a new avenue for crop diversification, farmer value creation and food-industry innovation.
The hidden constraint: what will feed the animals?
Rising protein demand also brings a less visible challenge—the availability and cost of feed.
The report identifies estimated shortfalls of 35.6% in green fodder, 10.5% in dry fodder and 44% in concentrate feed ingredients.
Climate pressures could further increase volatility in feed availability and production costs.
That makes the future protein equation considerably more complex. Expanding dairy, poultry and other animal-protein production requires not only more consumers and markets, but also adequate supplies of fodder, feed ingredients, water, energy and land.
Unless these constraints are addressed simultaneously, greater protein demand could place additional pressure on already stretched agricultural resources.
Farmers cannot be spectators in the transition
The report places producers at the centre of the transformation.
Smallholders account for approximately 72% of India’s milk production, while poultry and fisheries involve substantial numbers of contract growers, fragmented producers and smaller businesses.
The study therefore calls attention to the need for targeted finance, procurement reforms, technical assistance and producer consultation to ensure that farmers and smaller producers are not left behind as food systems evolve.
The transition, in other words, cannot be designed only around consumers and large food businesses. The economics of the farm gate will determine how sustainable the transformation ultimately becomes.
A trillion-rupee question disguised as a dinner-plate question
The report argues that coordinated action across policy, finance, food production and procurement can help India meet rising protein demand while reducing emissions, strengthening domestic value chains and supporting producer livelihoods.
“India is at a critical point in the development of its future protein system, but no single sector can address this alone,” said Rituj Sahu, Director – Protein Transition/Sustainable Food Systems (India), Asia Research & Engagement.
“Government and regulators have a role in strengthening policy support, banks and investors in directing capital towards the transition, and food and agricultural businesses in improving production, procurement and protein diversification,” Sahu said.
He added that the ARE-FICCI partnership seeks to take the findings into “the policy, investment and business decisions shaping India’s future protein system.”
For industry, the transition could represent a substantial new market as consumer demand changes and domestic value chains expand.
Jyoti Vij, Director General, FICCI, said the report highlights how India’s changing protein landscape presents “a significant opportunity for industry to innovate, invest, and build resilient domestic food value chains.”
“In line with the vision of Atmanirbhar Bharat, industry can play a key role in meeting evolving consumer needs, strengthening domestic capabilities and creating new opportunities for growth across the protein value chains,” she said.
The question India must answer before 2070
The study’s projections do not suggest that rising protein consumption is inherently incompatible with climate goals. Rather, they underline the consequences of how that demand is met.
A future in which India relies predominantly on business-as-usual production could carry a vastly different environmental footprint from one built around better production practices, diversified proteins, stronger pulse value chains, domestic processing and producer-centric investment.
The numbers make the choice stark: 1.92 GtCO₂e a year under business as usual versus about 0.30 GtCO₂e under the integrated pathway modelled by the researchers.
India’s protein transition is therefore emerging as a challenge—and an opportunity—at the intersection of nutrition, agriculture, climate, manufacturing, investment and rural livelihoods.
The food on India’s future plate may be determined not merely by what consumers choose to eat, but by whether policymakers, farmers, scientists, financiers and food businesses can redesign the system that puts that food on the plate.