
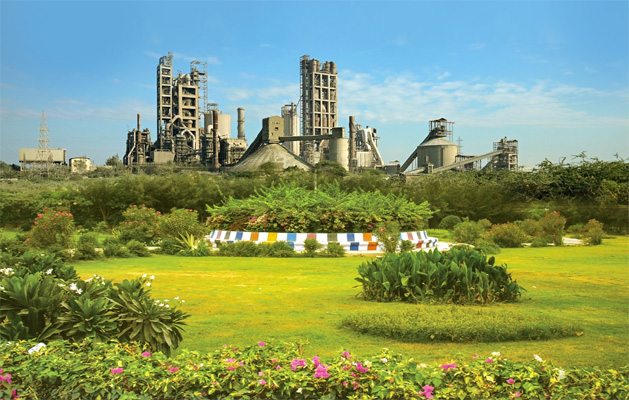
- CAPACITY BOOST: New grinding and blending facilities strengthen its manufacturing footprint in Uttar Pradesh and Maharashtra.
- SALES MIX IMPROVES: Trade share rises seven percentage points year-on-year to 78%, while premium products reach 47% of trade sales.
- FINANCIAL PRESSURE: Q2 revenue declines to ₹5,689 crore; operating EBITDA falls to ₹401 crore amid elevated costs and a changing business mix.
- READY-MIX MOMENTUM: Quarterly RMC volumes grow 19% year-on-year to 1.07 million cubic metres.
- ONE CEMENT PLATFORM: Shareholders back the proposed merger with Ambuja Cements, clearing a key milestone before the NCLT process.
- GREEN GROWTH: Green-power share increases to 34.4%, while the company’s sustainability assessment score improves.
NE BUSINESS BUREAU
AHMEDABAD, OCTOBER 28
ACC Limited is expanding its manufacturing muscle even as profitability faces pressure, adding 3.4 million tonnes per annum (MTPA) of cement capacity in the September quarter while pushing premium products, strengthening trade distribution and advancing its proposed amalgamation with Ambuja Cements.
The cement maker, part of the Adani Portfolio, reported consolidated revenue from operations of ₹5,689 crore for Q2 FY27, against ₹6,005 crore in the year-ago quarter. Operating EBITDA stood at ₹401 crore, compared with ₹846 crore a year earlier, while the operating margin narrowed to 7% from 14.1%.
Cement sales volume reached 9.72 million tonnes, against 10 million tonnes in Q2 FY26. The results reflect a challenging operating environment, including monsoon-related disruption, elevated energy costs, geopolitical uncertainties and constraints in domestic coal availability. The company also cautioned that comparisons were affected by higher volumes under the manufacturing and supply arrangement (MSA) with parent Ambuja Cements.
Vinod Bahety, Whole-time Director and CEO, ACC Limited, said: “We delivered a resilient performance in Q2 and H1 FY’27, supported by an improving sales mix and higher premium volumes. While the reported numbers are not strictly comparable due to the impact of MSA, the underlying business momentum remains encouraging, supported by our trade partners.”
Premiumisation becomes a strategic lever
ACC’s trade share increased seven percentage points year-on-year to 78%, while premium products accounted for 47% of trade sales. Blended cement’s share rose to 85% from 78% in the corresponding quarter last year, reflecting the company’s emphasis on product mix and value.
Bahety said the company’s growth remained trade-led, while institutional business was being strengthened through a comprehensive solutions approach focused on value and profitability.
He expects housing, infrastructure and capital expenditure to support cement demand, with improving pricing momentum potentially helping moderate the impact of higher fuel and energy costs.
3.4 MTPA added to manufacturing network
ACC commissioned a 2.4-MTPA greenfield cement grinding unit at Salai Banwa in Uttar Pradesh. Bulk Cement Corporation (India) Limited, an ACC subsidiary, commissioned a 3-MTPA cement blending unit at Kalamboli in Maharashtra, adding 1 MTPA of cement capacity.
Together, the projects added 3.4 MTPA to ACC’s capacity during Q2 FY27, strengthening its ability to serve key markets.
Ready-Mix Concrete (RMC) emerged as another growth driver. Quarterly volumes increased 19% year-on-year to 1.07 million cubic metres, taking first-half volumes to 2.04 million cubic metres, up 18%.
One cement platform moves closer
ACC shareholders approved the proposed amalgamation with Ambuja Cements at the NCLT-convened meeting on September 29, 2026. The scheme secured the requisite statutory and public-shareholder approvals, with more than 95% and 99% of votes cast by ACC and Ambuja shareholders, respectively, supporting the proposal.
The scheme will now proceed to the National Company Law Tribunal (NCLT) for sanction, subject to the remaining statutory and regulatory approvals.
The proposed consolidation is intended to simplify the corporate structure, improve manufacturing and logistics coordination, optimise resources and unlock operating synergies. Completion is expected during FY27, subject to approvals.
Green power and financial strength
ACC increased its green-power share to 34.4% from 30.3% a year earlier. Its 2025 S&P Global Corporate Sustainability Assessment net score was revised upwards from 72 to 82, while its gross score remained 89 out of 100.
The company also reported a water-positive status of 5.46 times and continued zero-liquid-discharge operations across its manufacturing facilities.
Its balance sheet remained debt-free, with net worth of ₹20,680 crore and cash and cash equivalents of ₹578 crore. ACC also retains CRISIL’s AAA/A1+ credit ratings.
For ACC, the next phase will involve converting expanded capacity, a stronger premium portfolio and closer integration with Ambuja Cements into sustainable earnings growth. The challenge is clear: translating manufacturing expansion into better margins as demand, pricing and energy costs evolve.