- Gujarat’s 3.08 lakh cumulative All Citizen NPS registrations point to a wider opportunity for retirement planning
- With 56.9% of workers self-employed, pension outreach needs to move beyond conventional employer-backed benefits
- Corporate NPS pitched as a “win-win” for employers and employees, with tax-related benefits and talent-retention advantages
- Dwivedi says inflation typically hovers around 5–6%, while SBI Pension Funds’ returns are “over 9%”—but future returns remain market-linked
- Sugam NPS, new retirement schemes and financial literacy drive expansion; AI-enabled personalised retirement planning is not currently offered
NE BUSINESS BUREAU
AHMEDABAD, SEPT 17
For Gujarat’s workforce, retirement security cannot begin only on the day a salary stops. With a large self-employed population, a growing corporate economy and women increasingly participating in the workforce, the challenge is to make long-term retirement planning accessible well before retirement approaches. SBI Pension Funds Pvt. Ltd. is seeking to widen the reach of the National Pension System (NPS) across the state, with a focus on corporate employees, individual subscribers and those outside traditional employer-backed pension arrangements.
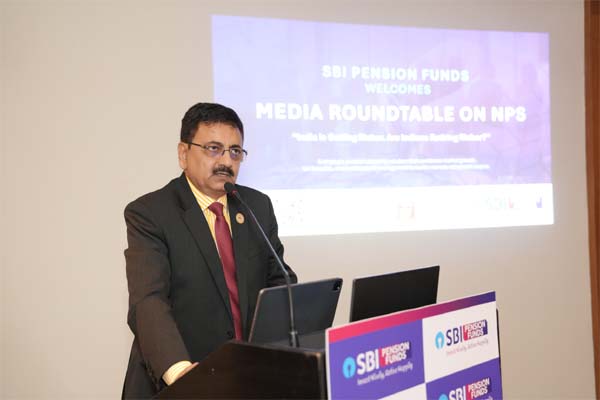
At a media briefing in Ahmedabad on Thursday, Pranay Dwivedi, Managing Director and CEO of SBI Pension Funds, outlined the company’s NPS outreach priorities, corporate-sector proposition and investment approach. Mukhtiar Singh, DGM, and Sandeep Panday, CSO, were also present.
According to figures shared by the company, Gujarat had approximately 3.08 lakh cumulative gross All Citizen NPS registrations through FY2024-25. The state recorded 49,895 new registrations during that year, including 11,064 by women.
The figures point to a substantial outreach opportunity. SBI Pension Funds estimates that around 90% of Gujarat’s workforce remains outside formal pension coverage, while the Periodic Labour Force Survey 2025 figures cited in its material show that 56.9% of workers are self-employed and around 17% are engaged in casual labour.
“Retirement planning needs to begin much earlier in an individual’s financial journey. With nearly 4.8 crore people in Gujarat in the 15–59 age group and more than half of the state’s workforce being self-employed, there is a significant opportunity to bring retirement planning to people who may not have access to traditional employer-backed benefits. NPS can play an important role in enabling individuals to build financial security through disciplined, long-term investing,” Dwivedi said.
Inflation and the real-return question
With inflation steadily eroding the purchasing power of retirement savings, Dwivedi was asked what real rate of return subscribers should target over the next 10–20 years.
“Inflation always hovers around 5 to 6 percent. We follow the RBI norms and our returns are over 9 percent, which can offset the impact of inflation,” he said.
At an illustrative nominal return of 9% and inflation of 5–6%, the inflation-adjusted return would be approximately 2.8–3.8% a year, before applicable charges and taxes. This is a mathematical illustration, not a forecast or assurance of future performance. NPS investments are market-linked, and actual returns depend on investment choices, market conditions and the period invested.
SBI Pension Funds says it follows a disciplined, long-term investment strategy, balancing growth and capital protection through diversified equity exposure, fixed-income strategies and selective inclusion of newer asset classes.
Corporate NPS: a “win-win” for employers and employees
Asked how SBI Pension Funds plans to substantially increase its presence among corporate employees and private-sector workers—and what subscriber growth it realistically targets—Dwivedi described Corporate NPS as a “win-win” for both employers and employees.
He cited cost-efficient benefits, simple administration, support for attracting and retaining talent, and an enhanced total-rewards proposition as advantages for employers. He also referred to tax-related incentives, zero-cost corporate registration and tax-free portability of superannuation funds to NPS.
SBI Pension Funds’ brochure cites a deduction under Section 37(1) of the Income Tax Act, 2025 among the benefits for employers. It also outlines employer-contribution provisions under Section 124(1), with different limits under the new and old tax regimes, subject to an overall ₹7.5-lakh limit as stated in the brochure. These provisions are presented here as company brochure claims; their precise statutory scope and applicability should be confirmed before being treated as general tax advice.
The brochure also presents Corporate NPS as a way to supplement retirement savings alongside EPF. It describes an option involving EPF contributions of up to 12% on the statutory wage ceiling of ₹15,000, alongside additional retirement savings through Corporate NPS, subject to applicable regulations and organisational policies.
For Gujarat’s companies, the proposition is to consider retirement benefits as part of workforce financial well-being. For employees and women, it is an opportunity to understand how regular contributions over time may help build retirement savings. For self-employed workers and gig workers, expanding access to information and suitable pension options remains a key part of the inclusion challenge.
The company’s stated focus is to expand adoption across retail and corporate segments, while promoting financial literacy and future readiness.
Digital access, but no AI-led personalised retirement planning yet
Asked whether artificial intelligence, predictive analytics and digital platforms could help provide personalised retirement planning rather than a one-size-fits-all investment approach, Dwivedi said the company does deploy digital technology, but does not currently offer such personalised planning.
SBI Pension Funds is strengthening its digital capabilities through its upcoming web application, Sugam NPS, which forms part of its broader outreach strategy. The distinction is important for prospective subscribers: digital development is under way, but AI-enabled, individually tailored retirement planning was not presented as an existing service.
More choices under the Multiple Scheme Framework
The company also highlighted the NPS Multiple Scheme Framework (MSF), which offers subscribers a wider range of investment choices. Its material refers to greater flexibility in asset allocation and the inclusion of additional asset classes such as Alternative Investment Funds (AIFs), Real Estate Investment Trusts (REITs), Infrastructure Investment Trusts (InvITs) and Gold ETFs.
Under the framework, SBI Pension Funds has introduced two schemes: SBI PF NPS Jeevan Swarna Retirement Yojana, intended for individuals with a higher risk appetite, and SBI PF NPS Akshay Dhara Retirement Yojana, which offers a balanced mix of equity and fixed income.
The company also highlighted a Retirement Income Scheme designed to enable subscribers to receive regular payouts after retirement without exiting the NPS framework. These developments form part of a broader effort to make retirement savings more adaptable to different life stages and investor needs.
A retirement conversation for every household
Rising life expectancy, healthcare costs and changing family structures have made retirement planning a matter for households—not only individuals approaching retirement. For working women, self-employed families and parents planning for their children’s future, the questions include when to begin saving, how much to contribute, how much investment risk to take and how retirement income may eventually be accessed.
NPS provides a regulated, market-linked retirement savings framework, but it is not a guaranteed-return product. Prospective subscribers should review scheme features, charges, withdrawal and annuity provisions, tax treatment and investment risks before deciding whether it suits their circumstances.
SBI Pension Funds said it would continue expanding NPS adoption across Gujarat and India through corporate and retail outreach, digital capabilities and financial-literacy initiatives.